THE NEWS IN BRIEF
Joann Evonne Wik faces severe felony charges, including theft by swindle and financial exploitation, for systematically dismantling the financial security of an elderly Detroit Lakes couple. This case serves as a brutal reminder that unsupervised access, regardless of the relationship, inevitably invites fraud through check forgery and transaction card abuse.
THE CONSULTANT’S VERDICT
Let’s strip away the human tragedy of elder abuse for a moment and look at the mechanical failure here. The Detroit Lakes case is a microscopic version of a macroscopic corporate disease. The “elderly couple” represents your legacy Board of Directors or a complacent C-Suite, and the defendant represents that “trusted” employee who has been with the company for twenty years. In my time auditing across the GCC and North America, I have seen multimillion-dollar leakages that started exactly this way: a helpful insider taking over “burdensome” financial tasks for leadership that simply didn’t want to be bothered with the details.
The charges—check forgery, credit card fraud, and swindling—are the corporate equivalents of T&E abuse, P-Card fraud, and ghost vendor payments. In the corporate context, the “vulnerable adult” is an entity with weak governance structures. Under the IIA Global Internal Audit Standards effective as of January 2025 (and fully enforceable in this 2026 landscape), particularly Principle 13 (Fraud Risk Management), Internal Audit functions are mandated to evaluate the potential for fraud and the manner in which the organization manages fraud risk. If you are still relying on “trust” as a mitigating control because an employee is “like family,” you are not just negligent; under the current regulatory framework, you are complicit.
The psychological manipulation in this news story is identical to social engineering within a finance department. The perpetrator likely didn’t start with a massive theft. It started with small transactions to test the waters—a method known as “salami slicing.” When no alarms went off, the volume increased. Corporate victims often claim they were “blindsided,” but the data always tells a different story. The red flags—lifestyle changes, refusal to take vacation, possessiveness over financial records—are always there. Companies become vulnerable when they prioritize operational convenience over segregation of duties. If one person can initiate a payment and reconcile the bank statement, you do not have a finance department; you have a crime scene waiting to be discovered.
Furthermore, this case highlights the failure of detective controls. Detective controls are the safety net when preventive controls fail. In a robust audit environment, algorithms should have flagged the anomalous credit card patterns or the check sequencing irregularities immediately. The fact that this reached the level of felony charges implies a long duration of undetected activity. In the Middle East, high-velocity family conglomerates often face this specific risk profile—where the boundaries between personal loyalty and professional governance blur. The result is always the same: capital flight and reputational ruin.
THE RARE METHODOLOGY: “LIFESTYLE & BEHAVIORAL TRIANGULATION”
Traditional sampling is dead. To catch the “trusted insider” before they liquidate the company, you must implement Lifestyle & Behavioral Triangulation.
This is a high-friction, high-reward approach that moves beyond the ledger. It involves integrating three distinct data streams:
- HR Data: specifically flagging employees with privileged access who have not taken a block of five consecutive days of leave in 12 months.
- System Forensics: Analyzing login times and volumes. We are looking for the “Super User” who logs in at odd hours or modifies master data files (Vendor Master, Employee Master) frequently.
- External Lifestyle Indicators (OSINT): utilizing open-source intelligence tools to scrape public records for luxury asset purchases, new business registrations under the employee’s name, or civil litigation that conflicts with their known salary bracket.
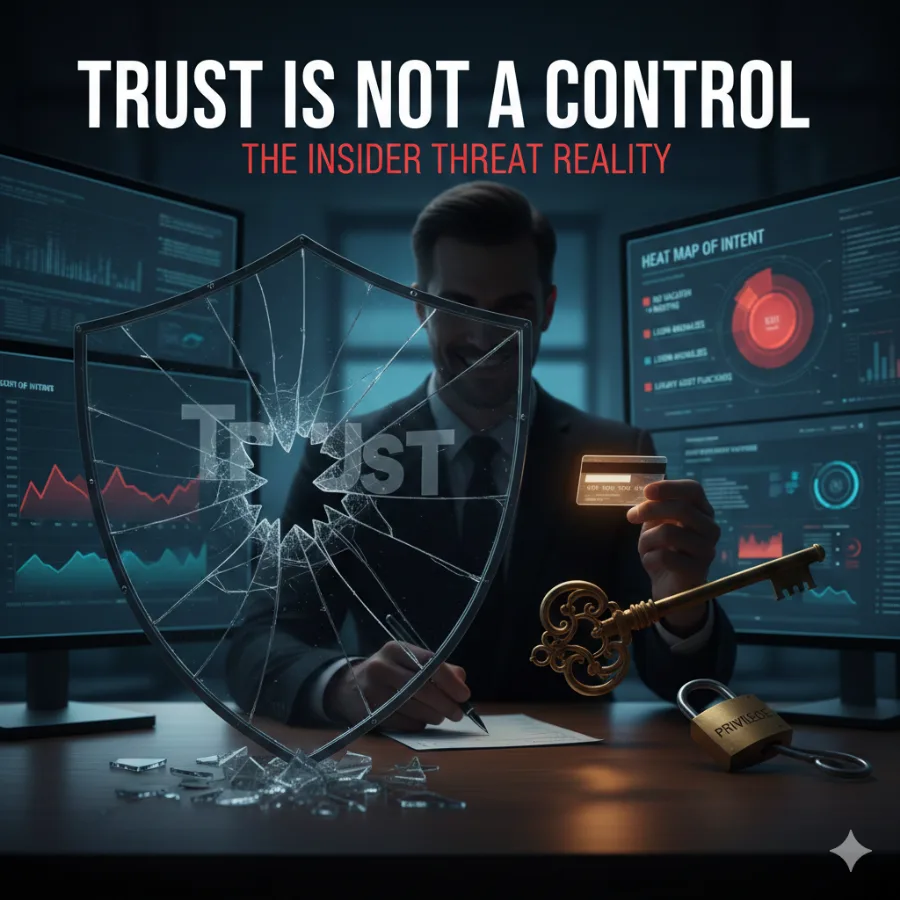
When these three streams intersect, you don’t just get a variance report; you get a heat map of intent. This requires Ethics Committee approval and tight legal coordination, but it is the only way to catch the sophisticated fraudster who knows your internal controls better than you do.
FINAL CALL TO ACTION
Stop auditing the process and start auditing the privilege; immediately review the logs of your top 5% most trusted users, because tenure is the most dangerous blind spot in your organization.